FHA Loan Pros and Cons: Key Advantages vs Drawbacks
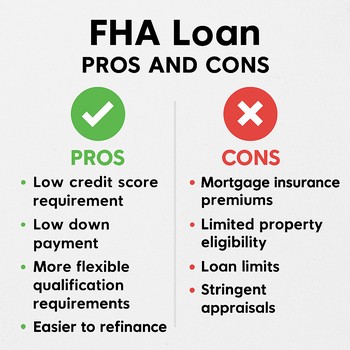 When deciding whether to pursue an FHA loan, understanding the pros and cons of FHA loans is essential to making an informed financial decision. FHA loans represent one of the most popular mortgage options for first-time homebuyers and borrowers with less-than-perfect credit, as they often qualify for FHA financing more easily than conventional mortgages. These government-backed mortgages offer significant advantages—including low down payments and flexible credit requirements—but also come with specific drawbacks like mandatory mortgage insurance that can increase your monthly payment and overall borrowing costs. This comprehensive guide breaks down the key FHA loan advantages and disadvantages to help you determine whether an FHA loan aligns with your homeownership goals.
FHA loans help millions of Americans achieve homeownership each year. The Federal Housing Administration backs these mortgages, making them less risky for lenders and more accessible for borrowers. However, like any financial product, FHA loans include both benefits and limitations that can impact your long-term economic health and total cost of homeownership.
Understanding the pros and cons of FHA financing can help you make an informed decision about your home purchase and whether to refinance into a conventional loan later. This guide provides an in-depth look at everything you need to know about FHA loans, from their flexible requirements to their potential drawbacks.
What Makes FHA Loans Different from Other Mortgages
FHA loans differ from conventional mortgages in several key ways. The Federal Housing Administration insures these loans, which means lenders face less risk when approving borrowers. This insurance protection allows lenders to offer more flexible qualification standards and lower payment requirements compared to traditional mortgages.
These government-backed mortgages typically require a minimum credit score of 580 for the lowest payment option. Borrowers can qualify with a score as low as 500 if they put more money down. This flexibility makes FHA loans attractive to borrowers who might not meet conventional loan standards and makes it easier to apply for an FHA loan.
The debt-to-income (DTI) ratio requirements for FHA loans also offer more leniency than traditional mortgages. Borrowers can qualify with a DTI ratio up to 57% in some cases, though most lenders prefer ratios below 43%. Use our DTI Calculator for FHA Loans to determine your qualify ratio and understand how your debt impacts your borrowing capacity.
FHA loans allow borrowers to receive gift funds from family members for their down payment and closing costs. This feature makes homeownership more accessible for buyers who may not have substantial savings but have supportive family members willing to provide financial assistance.
Key Advantages: FHA Loan Pros Explained
The primary advantage of FHA financing lies in its accessibility. FHA loan pros include the ability to qualify with lower credit scores, minimal down payment requirements, and flexible income documentation. These loans make homeownership possible for borrowers who might not qualify for conventional financing. The lower credit score requirements open doors for buyers working to rebuild their credit history after experiencing financial difficulties.
Low Down Payment Requirements. FHA loans require as little as 3.5% down when borrowers have credit scores of 580 or higher. This low down payment requirement helps buyers enter the housing market sooner rather than waiting years to save a larger amount. For many families, this difference represents the key to achieving homeownership. Our FHA Down Payment Calculator can help you estimate your required down payment based on your purchase price.
Flexible Income Documentation. The flexible income requirements of FHA loans accommodate various employment situations. Borrowers can include income from multiple sources, including part-time work, alimony, and even student loan payments in certain circumstances. This flexibility helps self-employed individuals and those with non-traditional income streams qualify for financing more easily. Learn more about FHA Loan Income Requirements to understand how your income affects your borrowing capacity.
FHA Streamline Refinance Option. FHA loans also offer benefits during the refinance process. The FHA Streamline Refinance program allows borrowers to refinance their existing FHA mortgage with minimal documentation and, in many cases, no appraisal requirement. This option helps homeowners secure lower interest rates without the hassle and expense of a complete application process.
Assumable Mortgage Feature. Another significant benefit involves the assumable nature of FHA loans. When interest rates rise, buyers can potentially assume the seller's existing FHA loan if they meet qualification requirements. This feature can provide substantial savings in higher-rate environments and protects you from rate increases.
Borrower Protection Programs. These mortgages also include provisions for borrowers facing financial hardship. FHA lenders offer various workout options, including loan modification and forbearance programs, to help borrowers avoid foreclosure during difficult times.
Key Disadvantages: FHA Loan Cons Explained
While FHA loans offer many benefits, they also include several significant disadvantages that borrowers must weigh carefully. Understanding the cons of an FHA loan is critical to making an informed decision about whether this financing option aligns with your financial goals.
Mandatory Mortgage Insurance Premiums. The most significant drawback involves mortgage insurance requirements that increase monthly payments and overall costs. FHA loans require two types of mortgage insurance premium payments. Borrowers pay an upfront mortgage insurance premium (UFMIP) of 1.75% of the loan amount at closing. Additionally, they must pay an annual premium that ranges from 0.45% to 1.05% of the loan amount, depending on the loan type and down payment amount. Use our FHA MIP Calculator to estimate these costs before you apply.
Mortgage Insurance for Life of Loan. Unlike conventional loans, FHA mortgage insurance premium payments continue for the life of the loan in most cases. Borrowers who put less than 10% down typically cannot remove this insurance, even when they reach 20% equity. This requirement means higher monthly payments throughout the entire loan term, significantly increasing your total borrowing cost. Only borrowers who put down 10% or more can potentially remove mortgage insurance after 11 years, and even then, refinancing is often the more practical solution.
Strict Property Standards and Inspection Requirements. Property standards for FHA loans can also present challenges. These mortgages require properties to meet specific safety and habitability standards that exceed typical conventional loan requirements. Homes must pass an FHA appraisal, which examines both value and condition. Properties that require significant repairs may not qualify for FHA financing. The FHA appraisal process is more rigorous and can lead to appraisal failures that delay or prevent the purchase.
Geographic Loan Limits. FHA loan limits vary by area and may restrict options in higher-cost housing markets. These limits determine the maximum amount borrowers can borrow through the FHA program. In expensive areas, these limits may fall below median home prices, forcing buyers to consider other financing options or look at properties below their target price range. Check current limits using our FHA Loan Limit Calculator.
FHA Loans vs Conventional Mortgages: A Direct Comparison
Understanding the differences between FHA and conventional loans helps borrowers make informed decisions. Conventional mortgages offer advantages that may benefit specific buyers, while FHA loans serve others better based on their financial situation and goals. For a deeper analysis, see our complete FHA vs Conventional Loan Comparison.
Conventional loans typically require higher credit scores, usually starting around 620 for most lenders. However, they offer the ability to remove private mortgage insurance once borrowers reach 20% equity, a significant advantage when evaluating FHA loan disadvantages. This feature can result in substantial monthly payment savings over time, sometimes $100-300+ per month depending on the loan amount.
The down payment requirements for conventional loans vary, but can be as low as 3% for qualified borrowers through specific programs. However, borrowers putting less than 20% must pay private mortgage insurance, which adds to monthly costs but can be removed later when equity reaches 20%.
Interest rates on conventional loans may be slightly lower than those on FHA loans for borrowers with excellent credit. However, FHA rates remain competitive and may actually be lower for borrowers with credit scores below 640, making FHA the more affordable option for many borrowers.
Conventional loans offer more flexibility in property types and locations. These mortgages can finance condominiums, investment properties, and higher-priced homes without the restrictions that apply to FHA financing. Borrowers seeking luxury homes or investment properties typically need conventional funding.
Who Benefits Most from FHA Loans
FHA loans are best suited for specific types of borrowers who can effectively leverage their advantages while minimizing their disadvantages. Understanding which borrower profile benefits most from FHA loans helps you evaluate whether this option is right for your situation.
First-Time Homebuyers. First-time homebuyers often find these loans particularly attractive due to their accessible requirements and educational resources. Many first-time buyers lack the substantial savings needed for larger down payments, making the 3.5% FHA option attractive. Learn more in our guide to FHA Loans for First-Time Homebuyers.
Borrowers with Fair Credit Scores (580-640). Borrowers with credit scores between 580 and 640 typically find better options with FHA financing than conventional loans. The flexible credit requirements and competitive rates make FHA loans more accessible for this credit range. Check our Credit Score Requirements Guide for details on how your credit score impacts your borrowing options.
Self-Employed Individuals and Non-Traditional Income. Self-employed individuals and those with non-traditional income sources may find FHA loans easier to qualify for than conventional financing. The flexible documentation requirements can accommodate various income types that traditional lenders might reject.
Buyers in Moderate-Cost Markets. Buyers in lower- to moderate-cost housing markets can take full advantage of FHA loan benefits without hitting loan limits. These borrowers can access affordable financing while staying within program parameters.
Military and Veterans. Military families and veterans should compare FHA loans with VA loan benefits. While VA loans offer superior terms for eligible borrowers, FHA loans provide an alternative for those who don't qualify for VA financing or want to preserve their VA eligibility for future use. See our FHA vs VA Loans Comparison for details.
Long-Term Homeowners. Borrowers planning to stay in their homes for many years may find the long-term costs of FHA mortgage insurance less concerning when they weigh the pros and cons of an FHA loan comprehensively. The stability and accessibility of FHA financing can outweigh the higher costs for long-term residents.
Making Your FHA Loan Decision: Key Takeaways
Choosing between FHA and conventional financing requires careful analysis of your financial situation, goals, and local market conditions. Consider your credit score, available funds for down payment, and long-term homeownership plans when evaluating options.
Calculate the total cost of each loan type over your expected ownership period. Include mortgage insurance costs, interest rates, and any potential savings from removing insurance or refinancing. This analysis helps determine which option provides better value for your situation. Our FHA MIP Calculator and Down Payment Calculator can help you estimate costs before you apply.
Read about current market conditions and interest rate trends before applying. Rising rates may make assumable FHA loans more attractive, while falling rates might favor conventional financing with its flexibility to remove mortgage insurance.
Work with experienced lenders who can explain the differences between loan types and help you understand which option best fits your needs. Many lenders offer both FHA and conventional loans, allowing you to compare options side by side.
Consider your plans for the property. If you expect to refinance or sell within a few years, the ability to remove mortgage insurance on conventional loans may not provide significant benefits. However, if you plan to stay long-term, this feature could save thousands. Start your application process early to give yourself time to explore different options. Pre-approval letters help you understand what you qualify for and make your offers more competitive in today's market. See our guide to FHA Loan Prequalification.
FHA loans continue to serve millions of borrowers successfully each year. These government-backed mortgages provide a pathway to homeownership for many who might otherwise struggle to qualify. However, they work best when borrowers understand both their advantages and limitations. The decision between FHA and conventional financing depends on your unique financial situation and homeownership goals. By understanding the pros and cons of each option, you can make an informed choice that supports your long-term economic health and homeownership dreams.
Frequently Asked Questions About FHA Loan Pros and Cons
What is the biggest disadvantage of an FHA loan?
The biggest disadvantage is the mortgage insurance requirement. FHA loans require both an upfront mortgage insurance premium (UFMIP) of 1.75% and annual premiums ranging from 0.45% to 1.05% that typically last for the life of the loan, increasing your monthly payment and overall cost. Unlike conventional loans where mortgage insurance can be removed at 20% equity, FHA mortgage insurance is nearly impossible to eliminate without refinancing.
Can I remove mortgage insurance from an FHA loan?
Removing FHA mortgage insurance is difficult. If you put down less than 10%, you generally cannot remove mortgage insurance without refinancing into a conventional loan. If you put down 10% or more, you may be able to remove it after 11 years. Most borrowers find refinancing is the most practical path to eliminating FHA mortgage insurance premium (MIP).
Are FHA loans only for first-time homebuyers?
No. FHA loans are available to any qualifying borrower, not just first-time homebuyers. However, FHA loans are especially popular with first-time buyers because of the flexible credit score and down payment requirements. Repeat homebuyers can also use FHA financing if they meet the program guidelines.
What credit score do I need for an FHA loan?
The minimum credit score for an FHA loan is 500, but you need a 580 or higher to qualify for the lowest down payment option of 3.5%. Credit scores between 500 and 579 require a 10% down payment. Checking your credit score early in the process can help you plan your FHA loan application strategy.
Is an FHA loan better than a conventional loan?
It depends on your specific financial situation. FHA loans are better for borrowers with lower credit scores or limited savings for a down payment. Conventional loans are often better for those with strong credit (620+) and larger savings, because conventional mortgage insurance can be removed once you reach 20% equity. Comparing both options side by side using your personal financial details is the best way to decide.
Connect With Us
Please share – it really helps