Do FHA Loans Have Mortgage Insurance? Complete Cost Breakdown
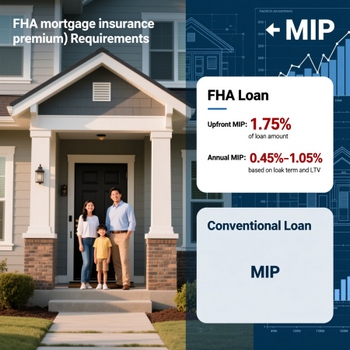 Yes, all FHA loans require mortgage insurance, regardless of your down payment size. Even borrowers putting down 20% or more must pay FHA Mortgage Insurance Premium (MIP). This mandatory insurance protects lenders if you default on your FHA loan payments. Understanding the costs, duration, and structure of FHA mortgage insurance is critical before committing to an FHA loan, as it significantly impacts your monthly payment and total loan cost over time. FHA mortgage insurance consists of two components: an upfront premium paid at closing and annual premiums added to your monthly mortgage payment.
What Exactly Is FHA Mortgage Insurance?
FHA mortgage insurance premium (MIP) is insurance that protects lenders who fund FHA loans. When you borrow through the FHA program, the federal government guarantees the loan, and you pay for that guarantee through MIP. Unlike private mortgage insurance (PMI) on conventional loans, FHA MIP is mandatory and typically permanent—even with a substantial down payment.
The FHA sets standardized MIP rates for all borrowers and lenders. Your credit score, income, or down payment size cannot change these rates. This standardization benefits borrowers with lower credit scores but costs more for those who could qualify for conventional loans with PMI.
The insurance premium funds the FHA's loan guarantee program, allowing the agency to offer mortgages to borrowers who might not qualify for conventional financing. This is why even borrowers with excellent credit and large down payments must pay MIP on FHA loans.
Understanding FHA Mortgage Insurance Requirements
All FHA loans require mortgage insurance regardless of down payment size. Current FHA mortgage insurance requirements include:
- Upfront mortgage insurance premium (UFMIP): 1.75% of the base loan amount, typically financed into your loan at closing
- Annual MIP: 0.15% to 0.75% of the outstanding loan balance, depending on loan-to-value (LTV) ratio, loan term, and other factors
- Minimum payment duration: 11 years for most loans
- Lifetime requirement: Entire loan term for loans with less than 10% down payment
Borrowers cannot avoid these premiums by shopping around or switching lenders. The FHA determines all rates nationally, and every FHA lender must collect the same insurance amounts.
How Much Does FHA Mortgage Insurance Cost?
FHA mortgage insurance costs include both upfront and ongoing components:
Upfront Premium (UFMIP): The upfront mortgage insurance premium equals 1.75% of your base loan amount and is due at closing. This cost is typically rolled into your loan balance rather than paid in cash. For example, on a $300,000 FHA loan, your upfront mortgage insurance cost would be $5,250.
Annual MIP (Paid Monthly): The annual premium typically ranges from 0.45% to 0.85% of your outstanding loan balance annually (the FHA sets the exact rate based on your loan characteristics). This amount is divided by 12 and added to your monthly mortgage payment. For a $300,000 FHA loan with a 0.85% annual MIP rate, you would pay approximately $212 each month for mortgage insurance alone.
The annual MIP decreases slightly each year as your loan balance declines, though the rate itself remains constant for as long as MIP is required. This monthly payment amount appears on your mortgage statement alongside principal, interest, property taxes, and homeowners insurance.
FHA Mortgage Insurance Cost Example
Let's calculate the total MIP cost for a practical example:
- Home Price: $300,000
- Down Payment (5%): $15,000
- Loan Amount: $285,000
- UFMIP (1.75%): $4,987.50 (financed into loan)
- New Loan Amount: $289,987.50
- Annual MIP Rate: 0.85%
- Monthly MIP Payment: Approximately $206
Over a 30-year loan, you'll pay approximately $74,160 in MIP alone—a significant portion of your total interest costs.
Annual MIP vs. Monthly Mortgage Insurance Payments
The FHA calculates mortgage insurance on an annual basis but collects it monthly from borrowers. Your annual MIP gets divided by 12 months and added directly to your mortgage payment.
This monthly collection system makes budgeting easier for borrowers who prefer consistent payments over large yearly bills. The process is automatic—your lender collects the monthly MIP and forwards it to the FHA on your behalf.
Some borrowers ask if they can pay the entire annual MIP upfront to save money, but the FHA doesn't permit this. All borrowers must make monthly mortgage insurance payments as part of their regular mortgage payment throughout the loan term.
FHA MIP vs. PMI on Conventional Loans
Understanding the difference between FHA mortgage insurance and conventional PMI is essential when comparing loan options.
| Feature | FHA MIP | Conventional PMI |
|---|---|---|
| Mandatory? | Yes, always required | Only if down payment < 20% |
| Cost | Higher (typically 0.45-0.85% annually) | Lower (typically 0.3-1.5% annually) |
| Removal | Cannot be removed (unless refinance) | Removed at 20% equity or 78% LTV |
| Varies by Credit? | No, standardized rates | Yes, credit score affects rate |
| Duration | 11 years minimum; often lifetime | Until 20% equity reached |
Key Difference: PMI on conventional loans can be removed once you reach 20% equity in your home. FHA MIP often lasts for the entire loan term, resulting in significantly higher total costs over 30 years. This makes conventional loans more attractive for borrowers who can save for a 20% down payment and have good credit.
How Long Do You Pay FHA Mortgage Insurance?
The length of FHA mortgage insurance payments depends primarily on your down payment amount:
Less Than 10% Down: You pay MIP for the entire loan term—typically 30 years. This is the longest duration and results in the highest total insurance costs. A borrower with 5% down on a 30-year FHA loan will pay mortgage insurance for all 360 months.
10% or More Down: You pay MIP for a minimum of 11 years, after which the annual mortgage insurance premium is removed. For a 30-year loan with 15% down, you'd pay MIP for 11 years (132 months), then continue making payments without the insurance component.
15-Year Loans: Regardless of down payment, MIP lasts up to 11 years on 15-year FHA loans. The faster equity buildup and shorter term make these attractive for borrowers who can afford higher monthly payments.
Only refinancing or paying off the loan entirely removes MIP from an active FHA loan. If you have an FHA loan with less than 10% down, you cannot remove MIP while maintaining the FHA loan structure.
Can You Avoid FHA Mortgage Insurance?
No, you cannot avoid FHA mortgage insurance. All FHA loans require both upfront and annual premiums, regardless of down payment size. This is a fundamental feature of FHA lending.
However, you do have alternatives:
- Choose a conventional loan instead. If you can make a 20% down payment and have good credit, conventional financing eliminates PMI entirely.
- Consider a VA loan if you're military-eligible. VA loans require no mortgage insurance and no down payment.
- Explore USDA loans for rural properties. USDA loans have lower insurance costs than FHA loans for qualifying rural purchases.
- Refinance to a conventional loan later. Once you build equity to 20% and improve your credit profile, refinance out of your FHA loan.
Each alternative has different eligibility requirements. Compare FHA vs. conventional mortgages to determine which option best suits your financial situation.
Removing or Reducing FHA Mortgage Insurance Through Refinancing
Refinancing is the most effective way to eliminate FHA mortgage insurance payments. Once you've built sufficient equity, you can refinance into a conventional loan that doesn't require MIP.
Conventional Refinance: To refinance out of FHA MIP, you typically need 20% equity in your home and must meet conventional loan requirements, including a good credit score and stable income. When home values increase or your loan balance decreases significantly, refinancing becomes financially beneficial.
FHA Streamline Refinance: Alternatively, FHA Streamline refinances allow borrowers to reduce their MIP rate without full underwriting. However, FHA Streamline refinances do not eliminate mortgage insurance entirely—you'll continue paying MIP, though potentially at a lower annual rate.
Use the FHA MIP and upfront fee calculator to estimate your insurance costs before refinancing. Also read our complete guide to FHA Streamline refinance requirements to determine if you qualify.
Refinancing Decision Factors: Evaluate current interest rates, your remaining loan balance, estimated home value, length of time you plan to stay in the home, and the breakeven point on refinancing costs versus long-term savings. The right decision depends on your individual circumstances.

Frequently Asked Questions About FHA Mortgage Insurance
Do all FHA loans require mortgage insurance?
Yes. All FHA loans require mortgage insurance regardless of down payment size. Even borrowers with 20% or more down must pay FHA mortgage insurance premiums. This requirement is built into the FHA loan structure and cannot be avoided.
What is the current FHA mortgage insurance rate?
The upfront mortgage insurance premium (UFMIP) is fixed at 1.75% of the loan amount. Annual MIP rates range from 0.15% to 0.75% depending on your loan-to-value ratio, loan term, and loan amount. The FHA sets these rates nationally, and all lenders charge the same rates.
Can you remove FHA mortgage insurance before the required period?
No. While FHA MIP cannot be removed early through payment or refinancing, you can refinance into a conventional loan once you have 20% equity and meet conventional lending requirements. This eliminates the FHA insurance requirement entirely.
How is FHA mortgage insurance calculated?
FHA mortgage insurance has two components: (1) Upfront Premium = 1.75% of base loan amount, and (2) Annual MIP = your annual rate times the outstanding loan balance, divided by 12 for monthly payment. Use the FHA MIP calculator for accurate estimates based on your specific loan details.
What is the difference between UFMIP and annual MIP?
UFMIP (upfront mortgage insurance premium) is a one-time cost of 1.75% of your loan amount, typically financed into your mortgage. Annual MIP is an ongoing cost expressed as a percentage of your outstanding loan balance, paid monthly as part of your mortgage payment. Both are required on all FHA loans.
Will FHA mortgage insurance ever decrease over time?
Your monthly MIP payment decreases slightly each year as your loan balance declines. However, the annual rate percentage stays constant for as long as MIP is required. The insurance itself does not disappear unless you refinance or meet the minimum payment duration requirements.
How much can you save by making a larger FHA down payment?
A larger down payment reduces your loan amount and therefore your UFMIP cost. It also may reduce your annual MIP rate and shorten the required MIP payment period. If you put down 10% or more, you'll pay MIP for only 11 years instead of the full loan term. However, the insurance premiums themselves cannot be avoided.
Connect With Us
Please share – it really helps